Perfect Prefab Home Connection · Treasure Valley, Idaho

Modern Prefab.
Expert Guidance.
Real Homeownership.

Manufactured, modular, and factory-built homes have changed dramatically. The financing, title requirements, and transaction process haven't gotten simpler. Charlie Wetherington specializes in exactly this segment — so you navigate it with a prepared advocate, not an agent learning alongside you.
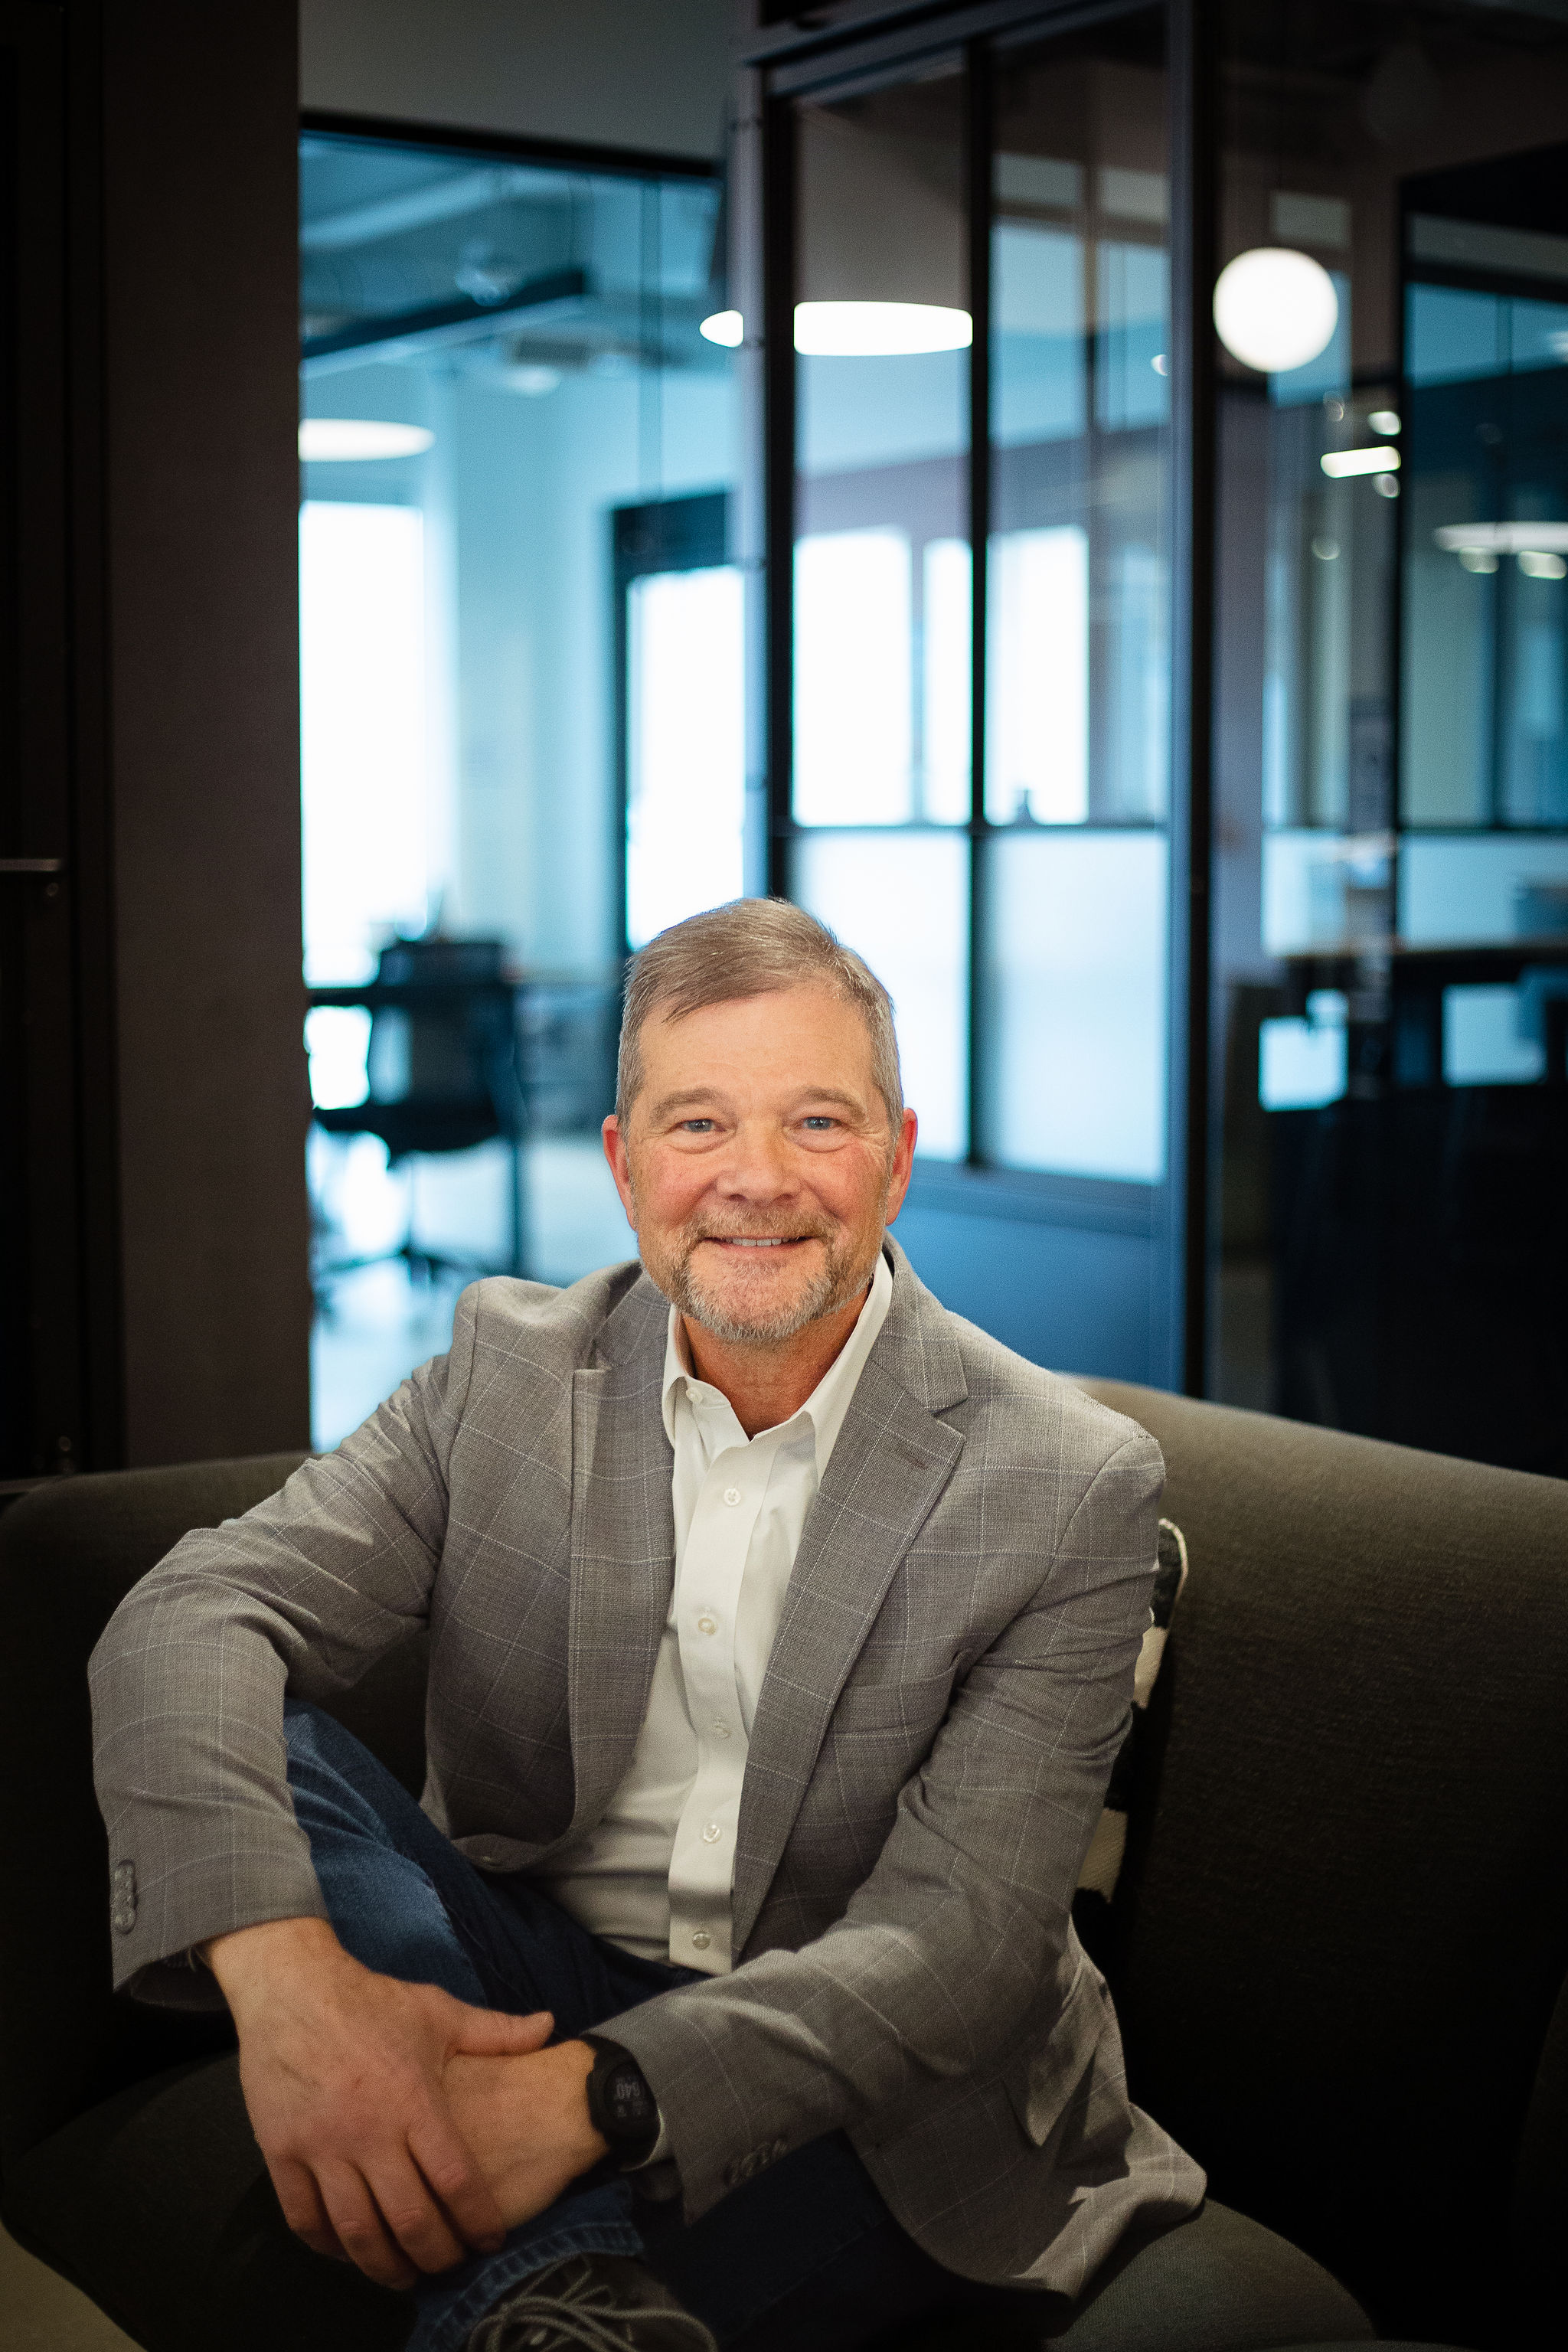
Charlie Wetherington — Prefab Home Specialist
Charlie Wetherington
Prefab Home Specialist · MHC Agent

“Prefab, mobile, and modular homes offer unique flexibility in placement and price point — making homeownership accessible to more of our community. Whether the property sits on rural acreage or a leased-land lot, I have the experience to guide buyers and sellers to a successful closing.”

Brokerage
My Home Connection · REAL Broker LLC
License
AB30242 · Licensed in Idaho
Segment
Prefab · Manufactured · Modular
Market
Ada & Canyon County, Idaho
Understanding Your Options

What "Prefab" Actually Covers

Most buyers come in thinking "prefab" means one thing. It doesn't. The term covers a range of construction types — each with different financing rules, title treatment, and resale characteristics. Knowing the difference before you start searching matters.

HUD-Code

Manufactured Homes

Built entirely in a factory to federal HUD standards and delivered to site. Financing depends on whether the home is on a permanent foundation (real property) or not (chattel/personal property). This distinction drives everything — lender eligibility, appraisal approach, and title treatment.

State Building Code

Modular Homes

Factory-built in sections, transported, and assembled on a permanent foundation to the same state residential building codes as site-built homes. Classified as real property from day one. Conventional, FHA, VA, and USDA financing all apply — and modern modular is indistinguishable from site-built in finish quality.

Panel Systems

Panelized Construction

Wall panels, floor systems, and roof assemblies are manufactured in a controlled factory environment and assembled on-site. Faster than traditional stick-built, treated as site-built construction for financing purposes. Common in custom and semi-custom builds where speed and quality control matter.

Premium Factory-Built

High-End Prefab

A growing segment of architect-designed, factory-precision homes at price points that rival or exceed site-built construction. Companies like Dvele and others are redefining what factory-built means. These are not your grandfather's manufactured homes — and buyers who've toured them know it immediately.

Community Living

Land-Lease Communities

You own the home; you lease the land. Common in manufactured home communities throughout Ada and Canyon County. Monthly lot rent applies. Financing options differ from owned-land transactions, and resale dynamics are different. Understanding what you're buying before you buy it matters here more than anywhere.

Bundled Packages

Land + Home Packages

Purchase land and place a manufactured or modular home on it — often in rural Ada County or Canyon County parcels. Financing a land-home package differs from a standard purchase. Lender selection, foundation requirements, HUD label verification, and title conversion are all part of this transaction type.

What Goes Wrong Without One

Why This Segment Requires a Specialist

Most residential agents can write a contract on a single-family resale. Prefab transactions introduce complexity that general agents routinely miss — not because they're careless, but because this segment has its own rules.

  • Financing Type Confusion

    Chattel loans, FHA Title I, conventional mortgage, VA — each applies in different circumstances based on foundation type and land ownership. Wrong lender selected at the start can kill a transaction at the finish line.

  • Personal Property vs. Real Property

    A manufactured home not affixed to a permanent foundation may be titled as personal property — not real estate. Title conversion to real property is required for most mortgage financing and affects how the home transfers at sale.

  • HUD Label Requirements

    Every manufactured home should have a HUD certification label (the "red tag"). Missing or removed labels can block FHA and VA financing entirely. Knowing how to verify this early prevents surprises that derail closings.

  • Foundation Requirements by Loan Type

    VA and FHA both have specific foundation requirements for manufactured homes. A home that doesn't meet them isn't automatically disqualified — but getting it to qualify requires knowing the standards before inspection, not after.

  • Appraisal Complexity

    Manufactured home appraisals require comparable sales of like-type homes. In some areas of the Treasure Valley, comps are limited. Understanding how appraisers approach this segment prevents pricing and expectation mismatches.

A prepared agent changes the outcome.

The issues above don't surface because sellers hide them — they surface because agents who don't know the segment don't ask the right questions at the start. By the time the problem appears, you've lost time, inspection fees, and sometimes the home itself.

Charlie's work in this segment means the right questions get asked before you're under contract — not during the fifteen days before closing.

Note: Prefab transactions can involve manufactured home-specific forms, disclosure requirements, and lender eligibility rules that vary by foundation type, land ownership, and loan type. Always confirm specific transaction requirements with your lender and agent before proceeding.

The MHC Standard

Built for the
Complexity You'll Face

Prefab transactions have more moving parts than standard resale. Financing options vary. Title treatment depends on details most agents never check. Lender eligibility shifts based on foundation type. My Home Connection agents work to a documented standard built for exactly these high-complexity situations.

Learn About My Home Connection →
Service Level Standards

Documented commitments — including the Two-hour response SLA, communication frequency, and transaction management. Not a promise. A standard.

Communication Accountability

You'll know what to expect, when to expect it, and who to call. That's not a style preference — it's a structural commitment baked into how MHC agents work.

Segment-Specific Preparation

Financing type, title treatment, foundation requirements, HUD labels — the right questions get asked before you're under contract, not during the fifteen days before closing.

Treasure Valley Guidance

How Prefab Pricing Works Here

Pricing in the prefab segment varies significantly by construction type, land situation, and finish level — and it moves with the market. Rather than publish numbers that go stale, here's what actually drives cost in Ada and Canyon County, and how each path is financed. Charlie can walk you through current ranges for your specific situation.

Type Land Situation What Drives the Price Financing Notes
Manufactured (land-lease community) Lot leased — monthly lot rent applies Home age and condition, community, lot rent terms Chattel loan or FHA Title I; fewer conventional lenders
Manufactured (owned land, permanent foundation) Land owned Land value, foundation, title conversion status FHA, VA, conventional all potentially available once titled as real property
Land + Home Package (manufactured) Land included in package Land cost, site preparation, home specification Combination land-home loans; lender selection is critical
Modular Home (on owned land) Land owned Home size and finish level, land cost, site work Treated as site-built; conventional, FHA, VA, USDA all available
High-End / Architect Prefab Varies Design, factory precision, finish level — can rival or exceed site-built Treated as site-built; standard financing applies

Pricing and community lot rents move with the market and vary by location, land cost, site preparation, and finish level. Ask Charlie for current ranges for your situation, and verify financing eligibility with your lender before committing to any purchase path.

Manufactured & modular homes — straight answers

What's the difference between a manufactured home, a modular home, and a mobile home?

They're legally different things. A manufactured home is built entirely in a factory to the federal HUD Code (in effect since June 1976) and carries a HUD certification label. A modular home is built in factory sections to the same state and local codes as a site-built house and is treated as site-built once assembled on its foundation. A mobile home, correctly used, means only a factory-built home from before June 1976. The category determines financing, titling, taxes, and insurance.

Is it hard to get a loan for a manufactured home in Idaho?

It's a different process, not a closed door. Financing falls into two broad categories: personal-property (chattel) loans, common when the home sits on leased or non-owned land, and real-property mortgages, available when the home and land are owned together and titled as real property. Which category applies, and on what terms, is a lender determination based on the specific home, the land, and the titling — which is why the right first step is knowing which conversation to start.

Can a manufactured home be converted to real property in Idaho?

Typically yes, when the home sits on land the owner holds and is permanently affixed — Idaho has a legal process for retitling a manufactured home as real property. It's one of the most consequential steps in this niche because titling drives the financing category, taxation, and resale paperwork. The requirements are specific, so verify the current process with your county and lender before relying on it.

Are modular homes built as well as site-built homes?

Modular homes are built to the identical state and local residential codes a site-built home in the same city must meet — then inspected, appraised, and titled the same way. Factory construction adds controlled conditions and repeatable precision. Quality still varies by builder, exactly as it does in site-built construction, which is why specification language and warranty scope deserve line-by-line reading before any contract is signed.

What does lot rent in a manufactured home community cover?

It varies by community, which is why the answer belongs in writing: ask for the lease and its term, the full rule set, the complete fee schedule, the history of rent adjustments, and what happens if you sell the home in place. Communities often include maintenance, amenities, and a genuine neighborhood; the structural trade-offs are rent that can change over time and personal-property titling for the home in most cases.

Can I put a manufactured home on family land in the Treasure Valley?

Often yes, and it's one of the most affordable paths to ownership here — but it rewards paperwork done early: whose name is on the deed, how the home will be titled, what the county requires for the placement, and what everyone has agreed to in writing. Requirements differ by county and zoning, so verify with the county before purchasing the home.

Do manufactured homes come with warranties?

New manufactured and modular homes typically carry warranties — and the details matter more than the word. Factory, dealer, and installer responsibilities can be separate, so ask for the scope and duration of each in writing, and confirm who is responsible for the foundation, tie-downs, and utility connections. For the home itself, specification language should pin down brands and grades, not “builder standard.”

Do I need my own agent to buy a manufactured or modular home?

Dealers and communities have representatives — and they represent the seller's side. Having your own representation means the specifications, the contract, the titling, and the land question get read on your behalf. Buyer agent compensation is negotiated and outlined in the Buyer Representation Agreement. In many transactions the seller agrees to cover the buyer agent's commission. Ask your MHC agent for details specific to your situation.

Schedule Your Consultation

Let's Talk About Your Prefab Path

Whether you're just researching or ready to move, a single conversation with Charlie will clarify your financing options, the right home type for your situation, and what the process actually looks like in the Treasure Valley.

Charlie Wetherington
Prefab Home Specialist · My Home Connection

Charlie Wetherington is the MHC agent specializing in pre-fab and modular home transactions across the Treasure Valley, and the lead on MHC's Stepping Up community initiative. Charlie brings focused expertise to a segment of the market most agents treat as an afterthought, and represents MHC's commitment to community engagement.

The Manufactured & Modular Home Guide + The Prefab Buyer's Kit

The guide that finally makes the terminology plain — what these homes legally are, how the financing really works, and the land question — plus five working tools including the one-page Terminology Decoder. Free, complete, useful whether or not we ever meet.

By requesting the guide you agree to receive it by email plus occasional manufactured- and modular-home resources from My Home Connection by REAL Broker LLC. Unsubscribe anytime.

Prefer to talk first?

A note on buyer representation: Buyer agent compensation is negotiated and outlined in the Buyer Representation Agreement. In many transactions the seller agrees to cover the buyer agent's commission. Ask your MHC agent for details specific to your situation.